Buying or Selling Commercial Property in Victoria: How Does the CIPT Transition Loan Work?
Victorian commercial property buyers: learn how the CIPT transition loan defers stamp duty across 10 annual instalments and what happens on resale.
Victorian commercial property buyers: learn how the CIPT transition loan defers stamp duty across 10 annual instalments and what happens on resale.
Learn what identity and source-of-funds documents a Victorian property settlement may require from 1 July 2026 under new AML/CTF laws.
After you sign a contract of sale, you will generally pay your deposit to the real estate agent. Usually, this amount will be held by the agent until settlement takes place. After settlement occurs, the deposit will then be released to the vendor. A Section
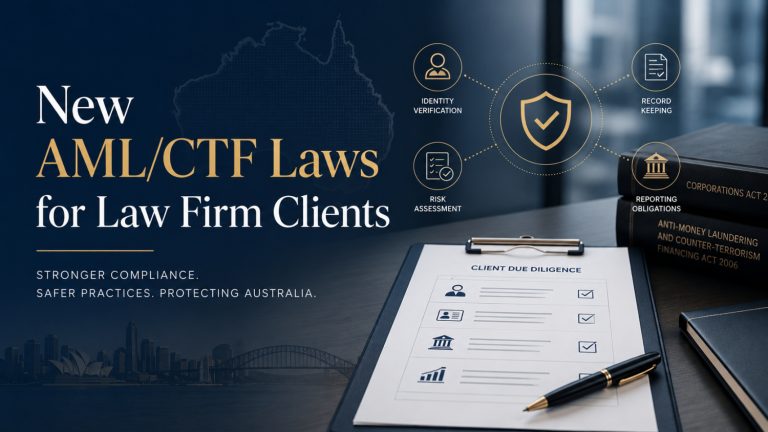
Anti-money laundering and counter-terrorism financing (AML/CTF) law help deter, detect and disrupt money laundering and terrorism financing. To align with international standards, the Federal Government introduced new AML/CTF law, which applies to law firms providing certain services in Australia from 1 July 2026. What changes
A lender may require a guarantor of a loan to obtain independent legal advice before giving any guarantee. A guarantor is an individual or a company, who will be responsible for meeting the borrower’s obligations under the loan agreement if the borrower fails to do
Stamp duty has long been a barrier to a buyer’s property transactions, whether they are entering the market for the first time or building a portfolio. The Victorian government has announced the abolishment of duty on eligible commercial and industrial properties (“CIPs”) (‘the reform’). From